Convertible loan Fundraising
Don’t be fooled by the discount and cap in a convertible loan
29 October 2024
A convertible loan can be a very effective financial instrument for startups, in that it removes the need to value a startup and bring an investor on board as a shareholder. Find out in this article how the discount and cap influence this operation and what they mean in terms of founder dilution.
What a convertible loan agreement must set out
The historical shareholders (including the founders) and the company should take care to include in the convertible loan agreement the elements common to all loans, such as the amount of the loan, the interest rate, the repayment terms, etc.
In addition to these elements, which are linked to any loan, they will be particularly vigilant regarding the specific elements organising the conversion of the loan and the specific requirements of the investors.
Why the discount and the cap deserve the most attention
In this respect, we draw your attention to the clauses organizing the discount and the maximum valuation (cap). These two important elements will affect the reference value of the company that will be used for the conversion of the loan and therefore the number of new shares that will be allocated to the investor.
These clauses can have a substantial impact on the dilutive effect of the investment at the time of conversion and therefore on the ‘cost in terms of shareholding’ of the conversion for the historical shareholders. The lower the reference value of the company, the more new shares the investor will receive in the company in return for the contribution of the debt relating to the loan and the more the participation of the historical shareholders will be reduced in relative terms.
The discount – the reward for investing before the others
The lender will generally receive a discount on the reference value of the company used for conversion.
The reference value of the company generally used for the conversion of the loan depends on the circumstances leading up to the conversion. If the triggering event is reaching the maturity date, the price per share is often determined on the basis of the market value set by a third-party expert or, if possible, using a predetermined formula. If the triggering event is a major financing event or an exit, the share price used will be the share price applicable for the financing event or exit.
This discount represents a profit for the lender due to the additional risk it has taken on by investing in the startup prior to the occurrence of the triggering event determining the reference value. This risk varies according to the circumstances of each situation and is difficult to quantify.
What discount rates apply in Belgium
The discount may be fixed or evolve over time. In practice, in Belgium, the fixed discounts usually vary between 20% and 30%. If the conversion of the loan is expected to take place soon after it has been taken out, typically for convertible loans taken out pending the forthcoming completion of a venture capital investment (known as a bridge), we generally recommend providing for a lower percentage that evolves over time.
The cap – the maximum valuation risk that the investor accepts
The parties may agree on a cap, i.e. a maximum valuation of the company for the conversion of the loan into shares.
This is a favourable mechanism for the investor, protecting him against a price per share that would be excessively high at the time of conversion, despite the application of the discount. Generally speaking, investors want to protect their investment against the startup becoming too successful, leading to a sharp rise in its valuation before their investment will be converted. It therefore corresponds to the minimum stake that the investor intends to receive at the time of conversion. Some investors tend to demand a limited cap that corresponds to their idea of the company’s valuation at the time of investment. At Beyond, we do not believe that this corresponds to the philosophy of such a clause.
The floor: the mirror protection for historical shareholders
In contrast to the valuation cap, the parties rarely stipulate a minimum valuation (floor) for calculating the price of the shares when the loan is converted into shares. Unlike the cap, this is a form of protection favourable to the historical shareholders.
It is important to specify that the cap/floor valuation must be applied after the discount has been applied.
The discount, the cap and the floor in numbers
The following examples illustrate the impact of a cap/floor:
– Investment : 250 000 €
– Discount : 30%
– Valuation cap of 3.000.000 EUR and valuation floor of 1.000.000 EUR (after application of the discount)
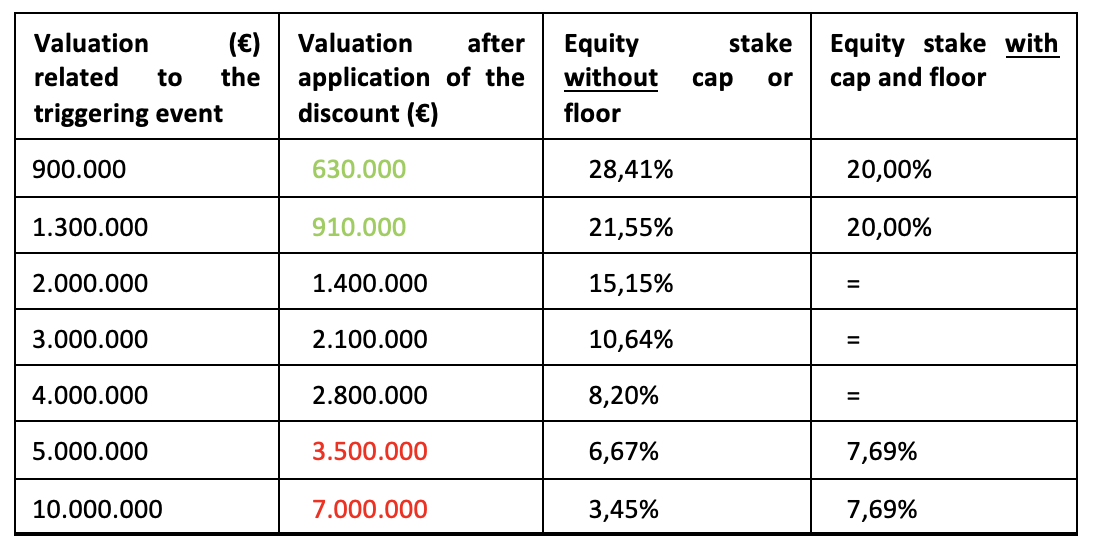
You can test other assumptions (valuation, discount, investment amount,…) on your own cap table using our convertible loan simulator.
FAQ
What is the discount in a convertible loan?
The discount is a reduction applied to the valuation of the company retained at the triggering event for conversion of the loan into shares. It compensates the lender for the additional risk taken by investing before the triggering event.
The lower the valuation used for the conversion, the more shares that investor receives and the more the historical shareholders are diluted.
What discount rates are common in Belgium for convertible loans?
In practice, fixed discounts usually range between 20% and 30%. Where conversion is expected shortly after the loan is granted (typically in the case of a bridge financing pending an imminent equity fundraising), we at Beyond generally recommend a lower percentage that evolves over time.
What is the cap in a convertible loan and who does it protect?
The cap is the maximum valuation of the company that can be used to determine the subscription price for the conversion of the loan into shares.
It protects the investor against the company’s valuation increasing significantly before conversion, which could otherwise result in a high subscription price for conversion despite the application of the discount.
By limiting the valuation used for conversion, the cap also determines the minimum stake the investor can receive upon conversion.
What is a floor in a convertible loan and why is it rare?
A floor is the minimum valuation of the company for calculating the subscription price for the conversion of the loan into shares.
Unlike the cap, it protects the historical shareholders by limiting the dilution that can result from conversion at a low valuation.
In practice, floors are rarely included in convertible loan agreements.
Is the discount applied before or after the cap in a convertible loan?
The discount is applied first. The cap or floor is then applied to the discounted valuation. This order should be explicitly stated in the convertible loan agreement, as applying the mechanisms in a different order can materially affect the conversion price and therefore the number of shares issued to the investor.
Specializing in tech and digital, Beyond Law Firm assists innovative companies with their legal affairs.
Let's talk